

Vola: Cash Advance & Credit
4.7

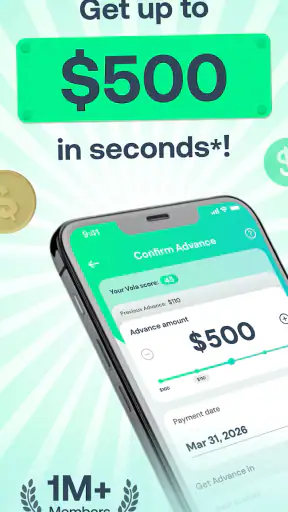
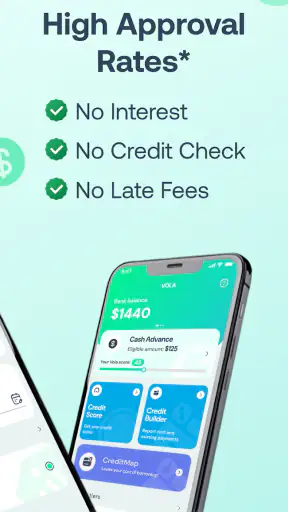
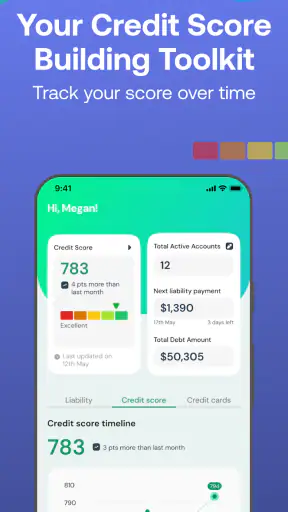
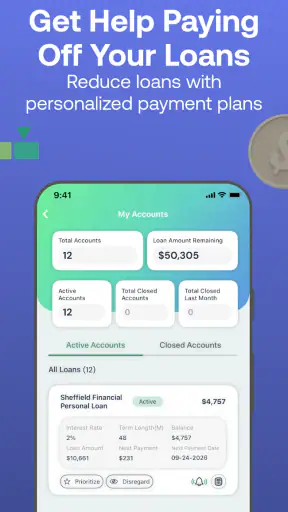
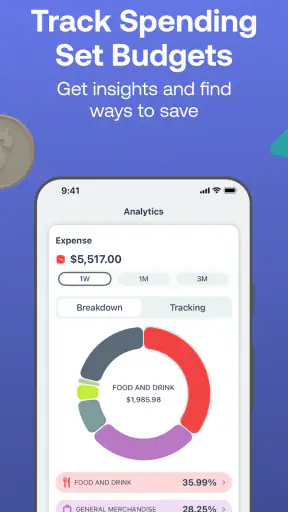
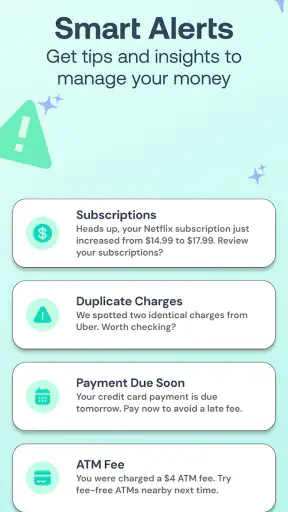
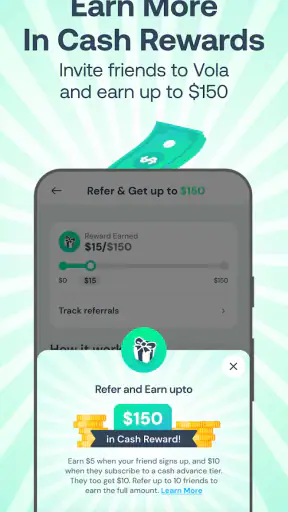
I see Vola: Cash Advance & Credit as a practical emergency-finance app rather than a complete replacement for a bank account or a long-term budgeting system. Its main appeal is straightforward: it brings cash-advance access, credit-building tools, budgeting, and spending tracking into one mobile experience. In my testing, that combination made the app most useful when I needed a clearer view of what was happening between paydays, not when I wanted a sophisticated investment or banking platform.
The important distinction is that Vola is designed around short-term financial breathing room. That can be valuable when an unexpected bill arrives before income does, but it also demands discipline. I would recommend it to someone who wants a simple way to monitor spending and explore an advance without going through a traditional credit-check process. I would be more cautious about recommending it to anyone who might use advances repeatedly to cover a permanent gap in their budget.
How Vola fits into everyday money management
Vola is a finance app from Vola inc. It is free to install, aimed at everyone, and available for devices running Android 9 or later. The app has been available since January 23, 2019, and its current version is 3.4.15. Those details matter because the experience is intended for ordinary smartphone users rather than finance specialists: the interface focuses on immediate money decisions, not complex financial products.
Its public reception is encouraging. Vola holds a 4.7 average from around eleven thousand ratings, with roughly two thousand reviews, and has passed half a million installs. I would not treat popularity as proof that an advance is suitable for every person, but it does suggest that the app has found a clear audience among people looking for accessible short-term financial tools.
The strongest part of the concept is the way several related tasks sit together. Instead of using one app to inspect spending, another to think about credit, and a separate service when a cash shortage appears, Vola puts those needs in the same place. That does not eliminate the need to check terms carefully, but it reduces the friction of switching between disconnected services.
The cash-advance experience is useful when timing is the real problem
A realistic example is a car repair that appears a few days before payday. If the expense is necessary and the person already knows the money is coming, an advance may be less disruptive than an overdraft or a high-cost borrowing option. Vola’s no-credit-check positioning makes the app particularly relevant to people whose credit history does not reflect their current ability to manage a small short-term need.
That benefit has a boundary. Avoiding a conventional credit check does not mean borrowing becomes free, automatic, or risk-free. I would open every disclosure before accepting an advance and look at the total repayment obligation, timing, and any conditions attached to the request. The app can make access easier, but it cannot make an unaffordable expense affordable.
My practical advice is to treat an advance as a bridge with a clearly marked exit. Before requesting one, I would identify the exact income that will cover it, reserve that amount mentally, and check what remains for rent, food, transport, and other fixed commitments. This small habit is more important than the convenience of the request itself. Without it, a helpful bridge can become a cycle of moving the same shortage from one pay period to the next.
Budgeting works best when you use it before the emergency
The budgeting side is more valuable than it may first appear because it changes the question from “Can I get money now?” to “Why is this month tight?” I found that spending tracking is most useful when reviewed regularly, not only after an account balance becomes uncomfortable. Looking at recurring purchases, irregular bills, and small frequent expenses can reveal pressure points that are easy to miss in a bank statement.
One non-obvious workflow is to review recent spending immediately after income arrives, rather than waiting until the final week of the pay cycle. I would separate unavoidable commitments from flexible spending, then use the remaining amount as the real limit for the period. If Vola shows that a category is consuming more than expected, the information is useful even if I never request an advance.
This approach also helps distinguish a temporary timing issue from a structural budget problem. A single unusually large bill may be manageable with planning. Repeated shortfalls after ordinary weeks point to a deeper mismatch between income and expenses. Vola can help make that pattern visible, but the app cannot solve it by itself.
Credit-building should be treated as a long-term project
The credit-building angle may attract people who have limited or damaged credit histories. I appreciate that it is presented alongside budgeting rather than as an isolated promise, because responsible credit improvement depends on consistent financial behavior. I would not judge the feature by how quickly it appears to change anything. The more useful question is whether the user can follow the required process reliably and understand what is being reported or recorded.
This is another area where careful reading matters. Credit-related tools are not interchangeable with a traditional credit card, secured card, or a direct conversation with a financial counselor. Someone comparing options should consider the purpose of each product, the obligations involved, and whether the arrangement fits their broader plan. Vola is more appealing to me as an accessible starting point than as the only credit strategy a person will ever need.
A sensible routine would be to use the app’s spending view to build consistency first, then consider credit features only after the monthly budget is stable. That order reduces the chance of using credit-building tools while simultaneously creating new short-term pressure. It is a small but meaningful trade-off: the fastest-looking option is not necessarily the safest one.
Where the app feels more convenient than usual alternatives
Compared with a standard bank app, Vola is more focused on the moment when available cash and upcoming obligations do not line up. Bank apps are usually better for viewing balances, moving money, and managing established accounts, but they may not offer the same combination of an advance-oriented workflow and credit-focused guidance. Vola’s advantage is concentration: the relevant tools are organized around financial strain and planning.
Compared with a spreadsheet, it is easier to use casually and more likely to be checked during a busy day. A spreadsheet can be more flexible, especially for someone who wants custom formulas, multiple scenarios, or detailed household planning. Vola is the better fit for a person who will actually open a phone app regularly but would abandon a manually maintained budget after a week.
Compared with a conventional credit product, the app may feel more approachable for someone who wants to avoid a standard credit-check route. However, a traditional product can be preferable when the user needs a larger planned purchase, a longer repayment structure, or a clearly established credit account. The right choice depends on the size and duration of the need, not simply on how easy the first screen feels.
The main weakness is the temptation to confuse access with progress
My biggest reservation is behavioral rather than technical. An app that makes short-term cash easier to consider can be genuinely helpful during a one-off disruption, but it can also make repeated borrowing feel normal. The budgeting and spending tools are important safeguards, yet they only help if the user is willing to look at uncomfortable patterns instead of tapping through them.
I would also avoid treating the free download as the same thing as a cost-free financial solution. The app itself can be installed without paying, but any advance or related financial service should be evaluated on its own terms. Before confirming anything, I would read the final screen slowly, check the repayment details, and avoid assuming that a familiar-looking interface means the arrangement is identical to a bank transfer or ordinary paycheck access.
Another limitation is that Vola is not the right tool for every financial problem. It is not where I would go first for investing, detailed tax preparation, complex shared household accounting, or a full debt-management plan. Someone with multiple creditors or persistent missed payments would likely benefit more from professional guidance and a broader restructuring strategy than from another way to access short-term funds.
Who should use it, and who should look elsewhere
I think Vola is a strong candidate for users who have predictable income, occasional timing gaps, and a genuine interest in tracking spending. It can also suit people who are new to budgeting and want a less intimidating starting point than a blank spreadsheet. The combination of cash access and financial visibility is especially relevant when the user wants to understand the cause of a shortage rather than simply cover it.
It may be useful for someone rebuilding financial confidence after a period of irregular income, provided that advances remain exceptional and the budget is reviewed honestly. In that situation, the app’s value is not just the possibility of receiving money; it is the chance to notice whether spending habits are improving from one pay cycle to the next.
I would tell users with unstable income to be particularly careful. If the next payment is uncertain, an advance can create pressure at exactly the wrong time. I would also suggest that people with a comfortable emergency fund compare the app with simply using that reserve, since borrowing can be unnecessary when accessible savings already cover the bill.
People who want detailed control may prefer a dedicated budgeting application or a spreadsheet. Those who need established banking services may be better served by their bank’s own app. And anyone looking for a long-term solution to expenses that consistently exceed income should skip the advance-first mindset and address the underlying budget directly.
A practical way to get more value from the app
If I were setting up Vola for the first time, I would begin with observation rather than borrowing. I would review spending, identify fixed commitments, and note the dates when money normally arrives and leaves. This creates a baseline and makes it easier to recognize whether a future request is an isolated need or part of a recurring pattern.
Next, I would create a simple personal rule: no advance request without a written repayment plan in my own notes. The plan would name the expected income, the date it arrives, and the bills that must still be paid afterward. This is not a feature claim about Vola; it is a practical safeguard that keeps the app’s convenience from replacing judgment.
I would also check the spending view after any unusually expensive week. That timing can expose the difference between a genuine emergency and a collection of small discretionary purchases. The insight is easy to miss if the app is used only when the balance is low, because the most useful information often appears before the crisis.
Finally, I would revisit whether the app is still helping after several pay cycles. If the budget becomes clearer and advances remain rare, Vola is serving a constructive role. If every cycle ends with another request, that is a signal to pause and seek a different solution. The correct response may be reducing expenses, changing bill dates, building savings gradually, or getting outside financial advice.
My final verdict on Vola
Vola: Cash Advance & Credit succeeds because it connects an immediate need with tools that can encourage better awareness. Its most convincing use case is a financially responsible person facing a temporary timing problem who also wants a clearer view of spending. The app’s free entry point, Everyone age rating, and accessible approach make it easy to explore, while its strong user reception gives it credibility as a mainstream finance option.
Still, I would not present it as a universal answer to money stress. The no-credit-check approach may widen access, but it does not remove repayment responsibility. The app is at its best when used as a planning aid with occasional emergency support, not as a recurring substitute for income or savings.
My recommendation is therefore conditional but positive: try it if you want cash-advance access alongside budgeting and spending awareness, and if you can identify exactly how any advance will be repaid. Skip it if your shortfall is ongoing, your future income is uncertain, or you need comprehensive debt assistance. Vola is most valuable when it helps you make a better money decision, not merely a faster one.
4.7
2.05K Reviews
Pros
- Fast access to small cash advances when eligible
- Simple application process managed entirely in the mobile app
- No traditional credit check may help some users qualify
- Repayment dates and advance details are clearly displayed
- Can help cover unexpected expenses between paychecks
Cons
- Fees may make borrowing expensive for a short-term advance
- Approval
- limits
- and eligibility can vary by user
- Repayment is often scheduled automatically from your account
- Late or failed payments may lead to additional charges
- Not available in every region or to all income sources


